CHAMWE KAIRA
South Africa’s agribusiness confidence improved in the third quarter of 2026, with the Agbiz/IDC Agribusiness Confidence Index (ACI) rising eight points to 53, moving above the 50-neutral mark.
The latest reading indicates that South African agribusinesses are optimistic about business conditions after the index remained below the neutral level for two consecutive quarters.
The improvement was driven mainly by respondents in the financial services sector, grain trading, agricultural input supply and the feed industry, while other respondents maintained their views from the previous quarter.
The survey, conducted during the first week of September 2026, covered businesses across agricultural subsectors nationwide.
Despite the improvement, respondents raised concerns about a possible El Niño-driven drought during the 2026-27 production season, ongoing geopolitical tensions and their potential impact on input costs and trade disruptions.
Respondents also cited the slow process of opening additional export markets as a concern for the long-term growth of agriculture. Most of the ACI’s 10 subindices improved during the quarter.
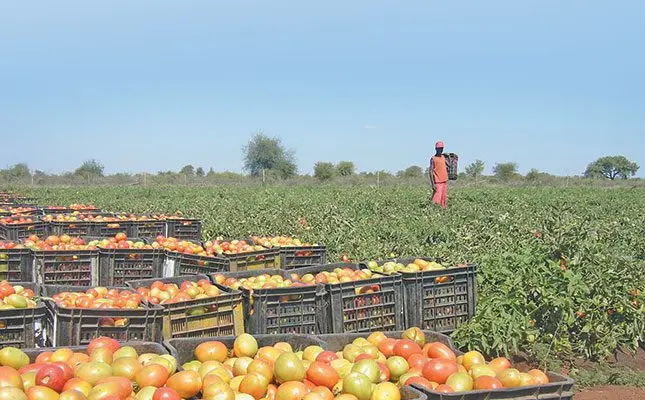
The market share subindex increased by six points to 67, reflecting favourable conditions following strong harvests in horticulture and field crops and generally improved export performance during the year.
The capital investment subindex recorded the largest improvement among the main indicators, rising 29 points from the second quarter to 63.
The increase comes despite weak tractor and combines harvester sales, with farmers anticipating difficult conditions during the 2026-27 production season.
The export volumes subindex increased by 21 points to 58, in line with stronger agricultural exports.
South Africa’s agricultural exports reached US$7.8 billion in the first half of 2026, an 11% increase from the corresponding period in 2025.
The general economic conditions subindex increased by 10 points to 38, although the report noted that it remained unclear whether economic data supported the improvement in sentiment at the time of the survey.
South Africa’s second-quarter GDP data was scheduled for release on September 8.
The turnover subindex remained unchanged at 67, supported mainly by ample harvests of grains, oilseeds, fruits and vegetables. The net operating income subindex also remained unchanged at 50.
However, the employment subindex declined by 10 points to 46. According to the report, agricultural employment data has shown a slight decline since the beginning of the year.
Quarterly Labour Force Survey data for the second quarter of 2026 showed that the farming sector employed 944 000 people, down 2% quarter-on-quarter but 4% higher than the same period in 2025.
The general agricultural conditions subindex fell by 25 points to 36, largely reflecting concerns about the expected El Niño drought and its potential impact on agricultural production in the 2026-27 season.
The financial-related subindices are interpreted differently from the other indicators, with a decline considered favourable and an increase indicating greater financial strain.
The debtor provision for bad debts subindex increased by 13 points to 46 during the quarter, reflecting expectations of difficult financial conditions due to higher input costs, animal diseases and drought concerns.
The financing costs subindex increased by 42 points to 58, indicating expectations of higher future financing costs and a possible increase in interest rates.
Agbiz and the Industrial Development Corporation said the latest ACI results reflected the favourable agricultural season that South Africa was leaving behind, but warned that uncertainty remained.
The report identified the potential El Niño drought, higher input costs, ongoing foot-and-mouth disease in the cattle industry, port inefficiencies and the need to open new export markets among the key issues facing agricultural and agribusiness stakeholders.
It also highlighted geopolitical tensions as a continued challenge because of their impact on farm input and shipping costs and the implications for South Africa’s efforts to expand agricultural export markets.
The Namibia Agriculture Union has said the country is expected to rely on imports for about 67% of its grain needs in 2026. This is slightly lower than the 73% recorded in 2025.
Local white maize purchases are expected to increase from 70,000 tonnes in 2025 to about 80 000 tonnes in 2026.
Wheat will remain mostly import-dependent. Only about 16% of national wheat demand is expected to be supplied locally.