Amupanda flags secret hearings, judicial interference, drafting flaws in proposed tax legislation
Desmarius Hansen
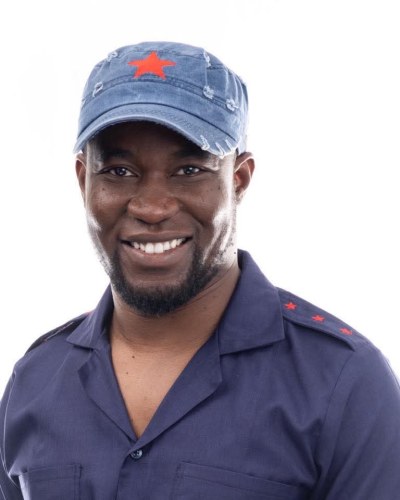
Affirmative Repositioning (AR) leader Job Amupanda has warned that Namibia’s proposed Income Tax Amendment Bill could face another constitutional challenge if passed in its current form, accusing its drafters of introducing provisions that undermine judicial transparency and conflict with existing legislation.
Contributing to debate on the bill in the National Assembly on Wednesday, Amupanda said legislation intended to correct unconstitutional provisions in the country’s 45-year-old Income Tax Act could itself create fresh constitutional vulnerabilities.
The Income Tax Amendment Bill, tabled by financeinister Ericah Shafudah, seeks to amend the Income Tax Act of 1981 to establish a Tax Court within Namibia’s High Court system.
The proposed court would hear appeals involving income tax, value-added tax (VAT) and other tax-related disputes, providing taxpayers with a specialised judicial forum to challenge decisions by the Namibia Revenue Agency (NamRA).
The bill also seeks to clarify the respective administrative responsibilities of the finance minister and NamRA commissioner, while setting out procedures governing tax court hearings.
Amupanda’s strongest objection centres on a provision stating that Tax Court hearings would not be open to the public, which he argued conflicts with Article 12(1)(a) of the Constitution, requiring court hearings to be held publicly.
He further warned that the provision could allow major corporations, including mining companies and international oil firms, to have tax disputes heard behind closed doors.
“Imagine a large mining corporation or an international oil company avoiding tax and disputing NamRA’s tax determination, using provisions we have written, to have their appeal hidden from public scrutiny,” he said.
He argued that the provision was particularly concerning because the proposed Tax Court would be established as a division of the High Court, making the blanket restriction on public access difficult to reconcile with the constitutional framework governing courts.
The criticism comes as parliament considers amendments to an Income Tax Act dating back to 1981, which previously gave the finance minister powers relating to the establishment of tax courts, judicial appointments and their closure.
Amupanda said those provisions were declared unconstitutional by the High Court on 27 March 2020 in Kruger v minister of finance and others.
The court had initially given parliament 12 months to remedy the constitutional defects, but Amupanda said the correction had been delayed for years.
Beyond the public-hearing provision, he identified what he described as a conflict between the proposed legislation and the Judiciary Act of 2015.
He argued that the bill gives the Judge-President responsibility for designating staff members to administer the Tax Court, despite the Judiciary Act assigning administrative responsibilities to the Executive Director of the Judiciary.
He also questioned provisions dealing with the appointment of a Tax Court president in the absence of the Judge-President, arguing that the proposed reference to the next most senior judge overlooks the existing office of the deputy Judge-President.
Amupanda further criticised the bill’s drafting, pointing to a definition that describes the Tax Court as the Tax Court established under the legislation, which he called a circular definition that provides no meaningful explanation.
He said several provisions, including those governing adjournments and court costs, were unnecessary given the existing powers and procedures of the High Court.
However, Amupanda made it clear that his criticism should not be interpreted as opposition to the bill’s underlying purpose.
“We support the fundamental intent of this bill. We will work to drastically strengthen its text,” he said.
He called for the legislation to be strengthened during the committee stage, while urging a broader national conversation on tax modernisation, particularly as Namibia positions itself around oil discoveries, green hydrogen and extractive industries.
He proposed dedicated transfer-pricing units, a review of double-taxation agreements and tighter scrutiny of tax holidays granted to multinational corporations.
Amupanda argued that Namibia’s tax reforms should also address illicit financial flows and ensure that multinational companies contribute fairly to the country’s economy.
He concluded that the country could not afford legislation that corrected one constitutional problem while introducing another.
“We cannot leave the Namibian taxpayer trapped in the tree between the lion of executive overreach and the black mamba of unconstitutional secrecy.”